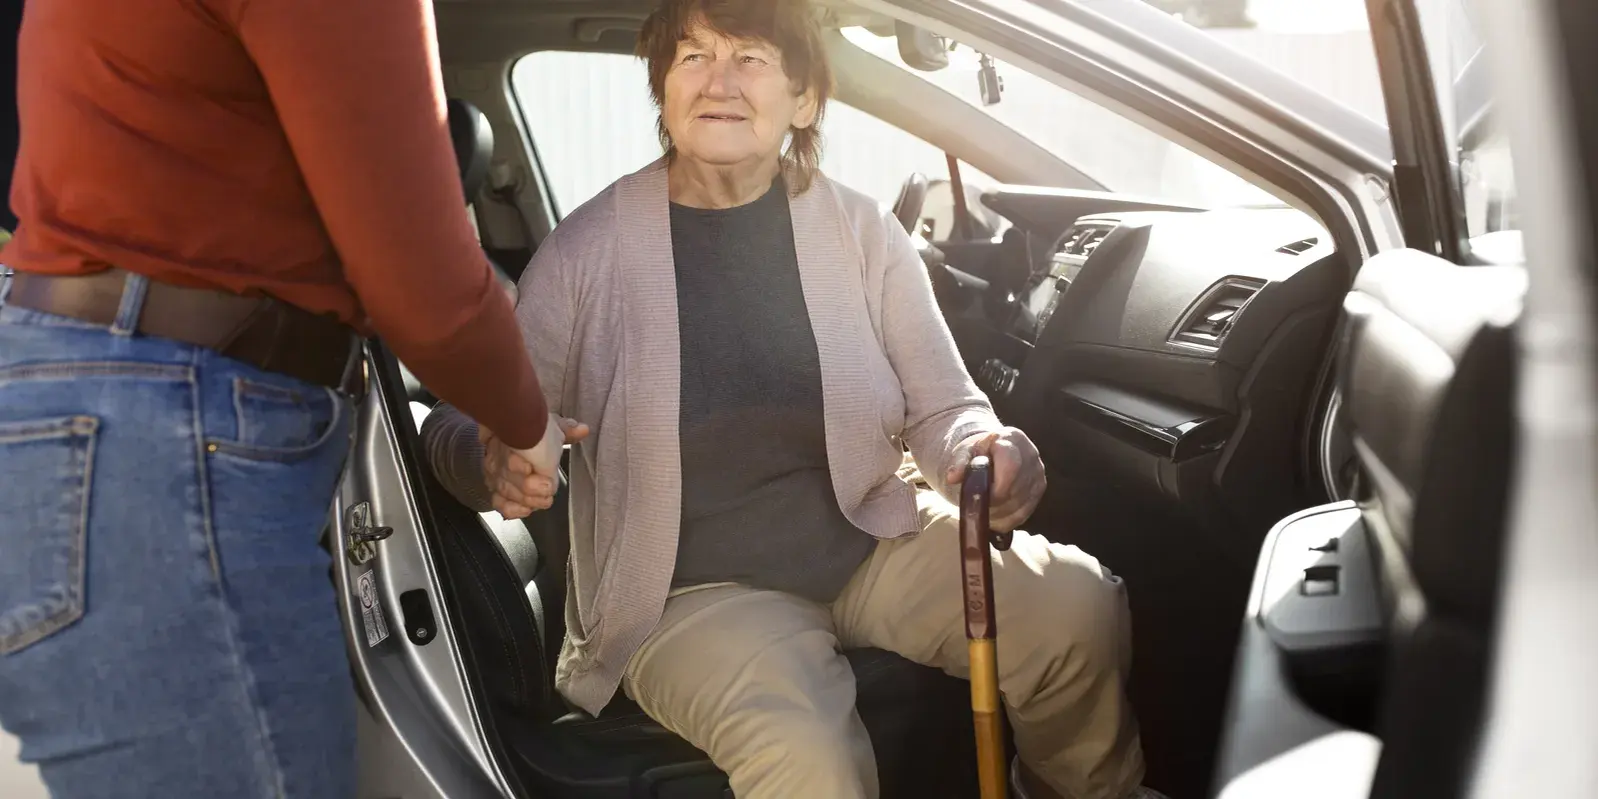
Planning ahead is not only about growing your financial resources but also about making sure those resources are protected. While life insurance is a familiar part of many long-term financial strategies, fewer people understand how much value an optional feature like a long-term care (LTC) rider can add to their overall protection plan.
An LTC rider is a simple add-on that can significantly expand the usefulness of your life insurance policy. It provides support during your lifetime if you need extended care, ensuring your coverage works for you in more than one way.
What an LTC Rider Does
At its most basic level, an LTC rider gives you early access to a portion of your life insurance benefit if you are unable to complete essential daily tasks such as bathing, eating, or dressing. It can also apply if you develop a chronic illness or cognitive condition that impacts your ability to care for yourself.
This benefit can help you pay for a range of long-term care services, including in-home assistance, adult day care, or nursing home support. Most policies allow you to access about 1% to 3% of your total death benefit each month, though some offer up to 4%. When used for qualified care expenses, these benefits are generally tax-free, helping reduce financial strain during a challenging time.
Why This Feature Matters
The need for long-term care is more common than many people realize. Roughly 70% of individuals age 65 and older will require some type of long-term care during their lifetime. Unfortunately, health insurance and Medicare typically cover only limited portions of ongoing care services.
Today, the median cost of a private nursing home room is more than $9,000 each month, while home-care assistance often averages around $30 per hour. For many families, these expenses can quickly erode retirement savings or force difficult decisions about how to manage care needs.
An LTC rider helps fill this gap by ensuring your life insurance policy can support the kinds of ongoing care many people eventually need. It offers an additional level of protection, giving you and your loved ones greater confidence that long-term care needs won’t jeopardize your financial well-being.
How It Works
Although the details vary among insurers, most LTC riders follow a similar structure:
- Triggering event: A healthcare professional must certify that you cannot perform at least two of the major activities of daily living (ADLs) or that you have a qualifying cognitive impairment.
- Waiting period: Policies typically include an elimination period—often 30 to 90 days—before benefits begin.
- Monthly benefit: You can use a set percentage of your policy’s death benefit each month, commonly between 1% and 4%, until you reach the policy’s maximum limit.
- Effect on death benefit: Any funds used for long-term care will reduce the amount your beneficiaries receive later.
- Cost: Adding an LTC rider increases premiums based on factors like age, health, and coverage amount.
The Benefits of an LTC Rider
An LTC rider effectively turns one insurance policy into a dual-purpose financial tool. If you require long-term care, the rider helps fund those needs. If you never need long-term care, your policy still provides the full—or remaining—death benefit for your beneficiaries.
This flexibility ensures that your insurance dollars go further. Instead of purchasing two separate policies, you can rely on a single plan that adapts to your needs over time. You also gain more control over the type of care you receive, whether you prefer in-home support or a facility-based option.
Using life insurance benefits instead of dipping into personal savings can also help you preserve more of your estate. And managing one policy with one premium makes financial planning simpler and more predictable.
Things to Keep in Mind
While an LTC rider offers meaningful advantages, it’s important to consider whether it fits your individual needs. Here are a few points to think about:
- Any money used for long-term care will reduce the eventual death benefit.
- Premiums are higher than a basic life insurance policy, though often still more affordable than standalone long-term care insurance.
- Some riders limit the total or monthly payout amount and may not automatically include inflation protection unless requested.
- Coverage rules and eligibility requirements differ among insurers, so reviewing your options carefully is essential.
Is It Worth It?
For many people, an LTC rider offers a balanced combination of protection, cost efficiency, and convenience. It provides access to funds if long-term care is needed, without requiring the commitment or expense of a separate policy. Depending on your plan, your beneficiaries may still receive a significant death benefit even if you use part of the funds for care.
The best way to determine whether an LTC rider is right for you is to look at a personalized estimate. This helps you understand how the rider might affect your premiums, the coverage amounts available, and how much flexibility it adds to your long-term planning.
The Bottom Line
Although no one can predict what the future holds, you can prepare thoughtfully. An LTC rider is an easy way to make your life insurance policy more adaptable, ensuring it offers support in more than one scenario.
If you’d like a tailored look at how this option could fit into your financial strategy, consider reaching out for a quote or consultation. Your insurance should grow and change with your needs—and an LTC rider is one way to make that happen.
Your friendly local guide to Medicare, health, and life insurance in Arizona. Get to know Javier.